

Onchain Highlights
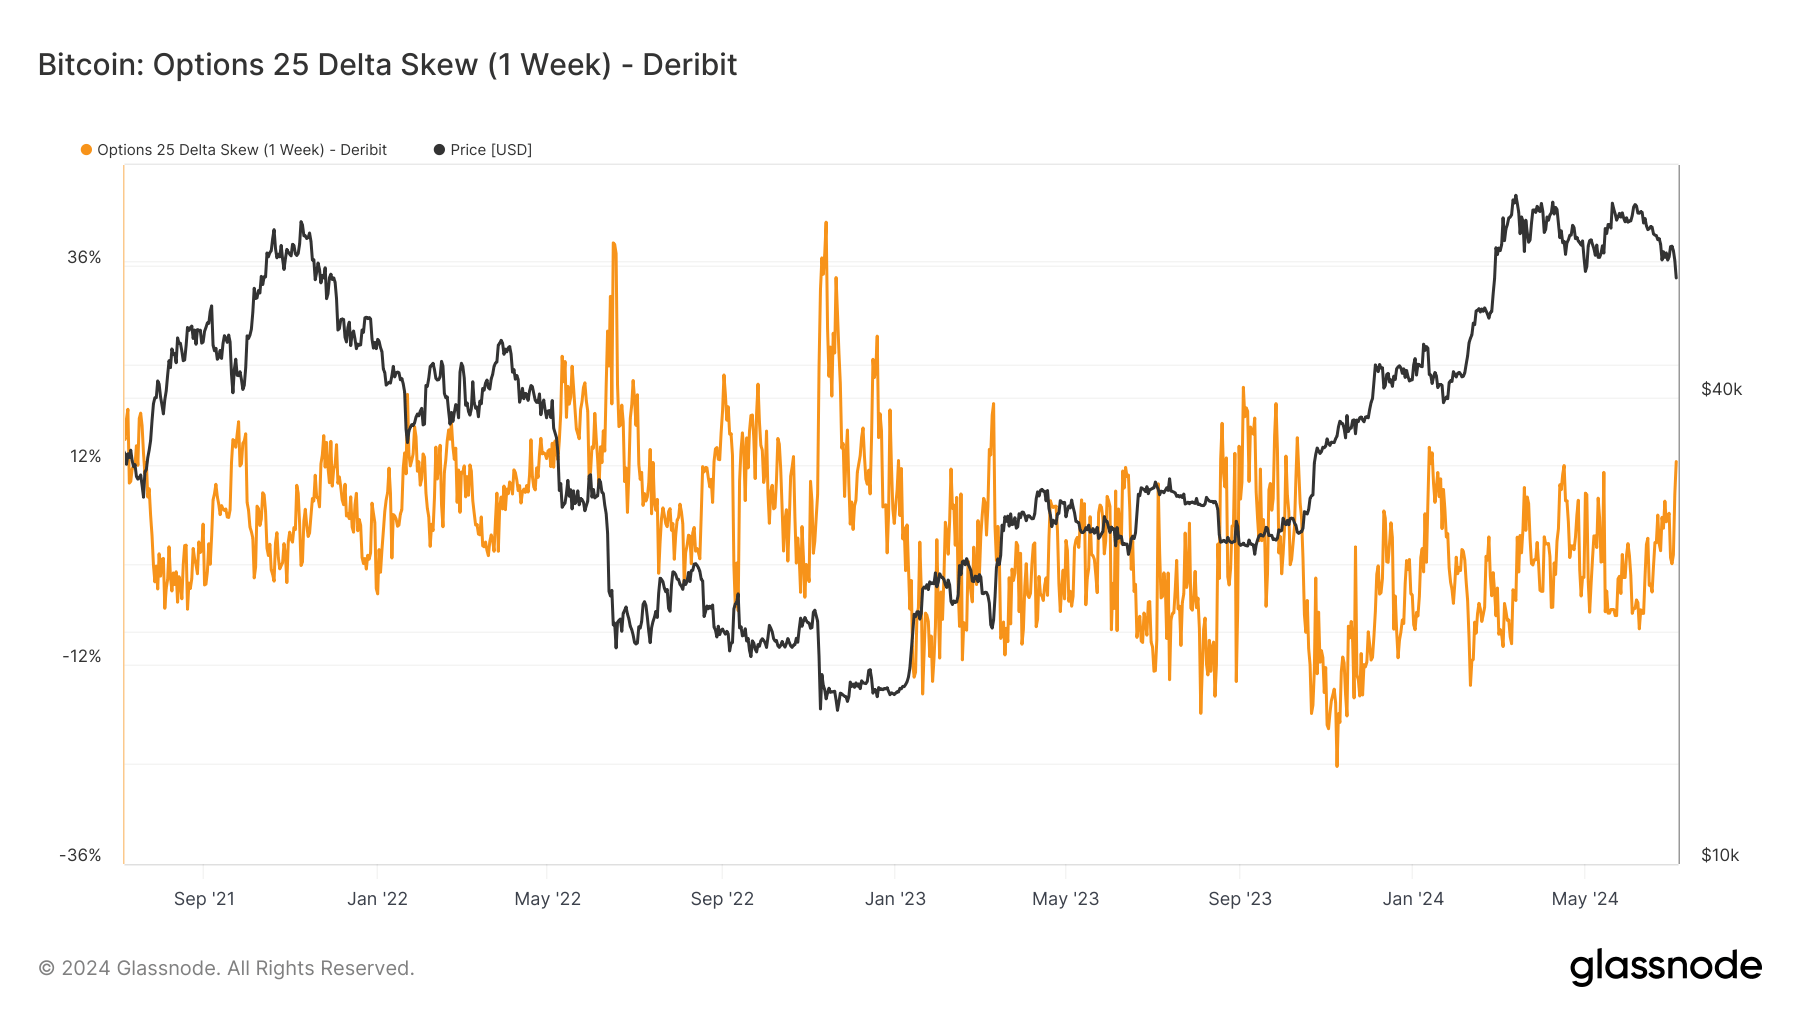
DEFINITION:Skew is the relative richness of put vs call options, expressed in terms of Implied Volatility (IV). For options with a specific expiry, 25 Delta Skew refers to puts with a delta of -25% and calls with a delta of 25% to demonstrate this difference in the market’s perception of implied volatility. 25 Delta Skew is calculated as the difference between a 25-delta put’s implied volatility and a 25-delta call’s implied volatility, normalized by the ATM Implied Volatility. This metrics focuses on option contracts expiring in 1 week.
Bitcoin’s options market has seen significant volatility in the 25 Delta Skew over the past several months. The one-week 25 Delta Skew metric on Deribit, which tracks the difference in implied volatility between 25-delta puts and calls, has fluctuated widely. Since January, the skew has ranged from lows of around -15% to highs exceeding 15%, highlighting the shifting sentiment and market perceptions of risk among options trad
We współpracy z: https://cryptoslate.com/insights/bitcoins-25-delta-skew-experiences-sharp-fluctuations-amid-correction/


